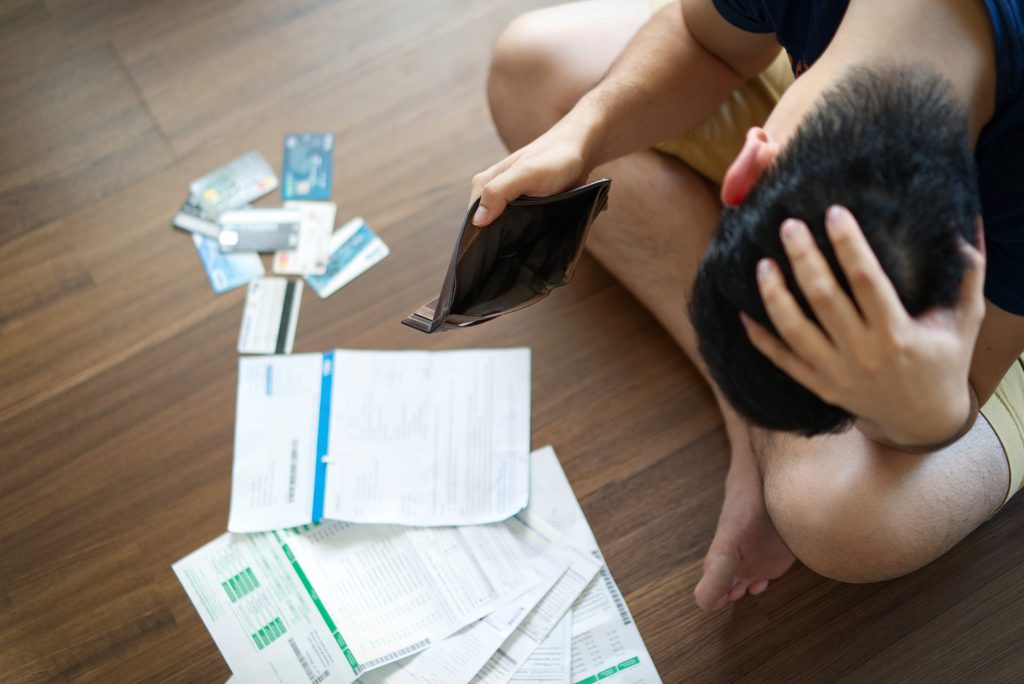
Nobody plans on an emergency. You haven’t penciled an unexpected medical bill, layoff or car repair on your calendar. And you certainly don’t assume you’ll be taking on a sudden home expense. So, no, while you didn’t plan on these emergencies, they’ve happened — and they’ve dramatically impacted your finances.
Now, you’re left wondering which bills to pay first and how to make your money stretch until things stabilize. Maybe you have to rely on your credit card more than you’d like. In these circumstances, protecting your credit might not seem like your most pressing financial concern.
But your credit can be an important financial resource, especially when you’re trying to get back on your feet. Missing payments, maxing out credit cards or taking on more debt than you can manage could make an already difficult situation even worse.
When you’re facing a financial emergency, protecting your credit doesn’t have to be complex if you follow a few key steps.
Sponsored by Sky Blue Credit is the most powerful solution to dispute errors on your credit reports, rebuild your credit, and optimize your scores.
Know What Has to Be Paid First
If you can’t pay every bill in full, start by separating your essential expenses from everything else. Naturally, you’ll focus on what you need for your daily survival, like a roof over your head and food on your table. With these things squared away, you can worry about transportation and insurance. Once you’ve factored in those expenses, it’s time to look at your credit card bills, loan statements and other debts to see which payments are coming due. You’ll also need to know what happens if you’re late on those payments.
What you discover may scare you. But you don’t have to handle it all alone. Your creditors and lenders might be more interested in helping you than you’d think. So, contact them before you miss a payment. They may have hardship programs, payment arrangements or other options that could give you some breathing room.
Contact them before you miss a payment. They may have hardship programs, payment arrangements or other options that could give you some breathing room.
Keep Making Your Payments If You Can
Your payment history is an important part of your credit score, so keeping up with at least your minimum payments can help protect your credit during a difficult period. This is why contacting your creditors and asking about your options is so important: A payment plan may reduce the size of your minimum payments or even temporarily defer payments.
In the meantime, if you’ve set up automatic payments, check your account balance. An automatic payment that causes an overdraft is the last thing you want when money is already tight.
Be Careful About Maxing Out Your Credit Cards
When an emergency hits, a credit card can seem like an easy way to cover an expense you truly can’t afford right now. Sometimes, using available credit is necessary. But before charging anything, think about how you’ll eventually pay that balance down.
Using a large portion of your available credit could also affect your credit score. If you’re already carrying balances, adding more debt may leave you with less room to handle another unexpected expense.
Sometimes, you may simply need to use your credit card. It’s not great, but it doesn’t have to be catastrophic. Keep track of what you charge and make a plan for paying it down when your financial situation improves.
It’s not great, but it doesn’t have to be catastrophic.
Sponsored bySky Blue Credit is the most powerful solution to dispute errors on your credit reports, rebuild your credit, and optimize your scores.
Check Your Credit Report
You likely didn’t have control over the circumstances that led to your financial emergency. But you do have the power to check your credit report and make sure that errors don’t damage your score.
Take a few minutes to review your credit reports for unfamiliar accounts, inaccurate payment information or other mistakes. You can also use this opportunity to make sure your current account information is being reported accurately.
Checking your credit report won’t hurt your credit score, and knowing what’s on your report can help you make smarter decisions when money is tight.
Avoid Taking on More Debt Than You Can Handle
When you need money quickly, it’s easy to focus on getting through the immediate crisis. Repayment can wait, right? Unfortunately, it’s not that simple. The loan or new credit that solves today’s problem could create an even bigger woe if the payments don’t fit your budget.
Before taking on new debt, look at the interest rate, fees, monthly payment and total cost. Make sure you understand what you’re agreeing to and have a realistic plan for repayment.
Give Yourself a Credit Recovery Plan
Hopefully, your immediate financial emergency will pass soon. When it does, and the dust settles, you’ll need to take stock of your finances. Look at your outstanding balances, payment history and available credit.
Once you’ve caught your breath and done your financial inventory, you should figure out how you’ll get your credit back on track. That might mean paying down a credit card balance or bringing a past-due account current.
Now that you’ve been through the chaos of a financial emergency, you’ll want to do anything you can to make things easier for yourself the next time circumstances have you a day late and a dollar short (literally). Building a small emergency fund is a good way to start. Even setting aside a little money each month can give you some cash to fall back on when your car needs a repair or another unexpected bill comes due.
You may also want to review your budget and look for expenses you could cut to funnel additional money to your emergency fund. Ideally, you’d like to have three to six months of living expenses saved in this fund; although, in a more economically uncertain climate, you should consider saving between six and 12 months of expenses, if possible.
Regardless, with an emergency fund in place, expenses won’t automatically go on a credit card.
You may not be able to protect every aspect of your finances during an emergency. But being proactive about your credit can help you limit the damage and put yourself in a better position when things get back to normal.
You may not be able to protect every aspect of your finances during an emergency. But being proactive about your credit can help you limit the damage.
And hopefully, things will get better for you, financially and personally. Hang in there.
Sponsored bySky Blue Credit is the most powerful solution to dispute errors on your credit reports, rebuild your credit, and optimize your scores.